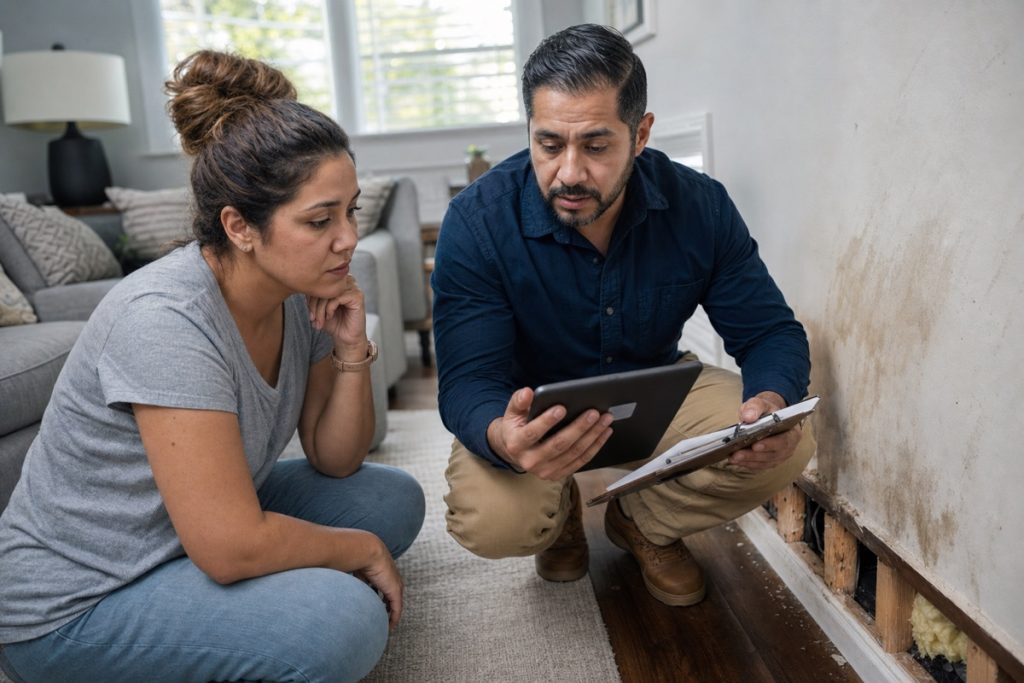
To file a water damage claim in Texas, you document the damage before you clean up, report it to your insurer promptly, mitigate further damage, and keep records of everything. Done in that order, most sudden-and-accidental water claims go smoothly. The mistakes that hurt claims almost all come from skipping a step.
Step 1 — Stop the damage and document first
Your policy requires you to prevent further damage (mitigate), but do it after you photograph and video everything. Wide shots and close-ups of every affected room and item, before you move or throw anything out. This evidence is what the claim is paid on.
Step 2 — Report the claim promptly
Call your insurer as soon as you reasonably can. Texas policies expect prompt notice, and delays give an insurer a reason to question the claim. Get your claim number and the adjuster’s contact.
Step 3 — Mitigate and keep receipts
Get a crew to extract and dry the structure fast — waiting and letting mold grow can actually reduce your payout, because insurers don’t cover damage you could have prevented. Keep every receipt and the crew’s documentation. (This is the cleanup phase.)
Step 4 — Work the estimate
The restoration crew provides moisture readings, photos, a written scope, and a line-item estimate — the format adjusters expect. Review the adjuster’s estimate against it; if it’s short, that’s a conversation to have before you accept.
Common mistakes that reduce a claim
- Throwing out damaged items before documenting them.
- Waiting to report or to start drying (letting damage spread).
- No paper trail — missing photos, receipts, or estimates.
- Assuming rising flood water is covered (it needs separate flood insurance).
Water damage and a claim to file? We document it the way adjusters expect. Call (713) 422-2550 — Houston, 24/7.
Frequently asked questions
What should I do first when filing a water damage claim?
Photograph and video everything before you clean up or throw anything out, then report the claim promptly. The evidence is what the claim is paid on.
Can waiting hurt my claim?
Yes. Insurers don’t cover damage you could have prevented, so delaying drying and letting mold spread can reduce your payout. Mitigate promptly and keep records.
Is flood water covered by my homeowners policy?
No — rising flood water needs separate flood insurance (NFIP). Sudden internal water like a burst pipe is what a homeowners policy typically covers.
Water damage in your home right now?
Don't wait for it to spread. Talk to a Houston crew, 24/7.
Call (713) 422-2550More Houston water damage guides
Water spreading right now? Don't wait.
Every hour costs you more in damage. Call now and get a Houston crew moving.